All Categories
Featured
Exploring How Whole Life Insurance Functions
Table of Contents
1 Investopedia - How Whole Life Insurance Works. 2 Thrivent Whole life insurance: Pros, cons & who it's right for. 3 Forbes - What Is Whole Life Insurance?
Accessed June 18, 2026. 4 Forbes - What Is Variable Life Insurance? Upgraded November 26, 2024. . Accessed June 18, 2026. Content within this short article is provided for basic informational functions and is not provided as tax, legal, health, or financial recommendations for anybody or for any particular situation.
For complete information, including schedule and expenses of Aflac insurance coverage, please contact your local Aflac agent/producer. Aflac life prepares A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York City, Policies NY68200, NY68300 and NY68400.
Affordable Life Insurance Strategies for Veteran Families
In Delaware, Policy A68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Not available in Virginia. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York City, Policy: NYQ60100M. Not offered in Virginia. In AR, DE, ID, OKAY and VA: Policies ICC21-AFLLBL21 and ICC21-AFLRPL21; and Riders ICC21-AFLABR22, ICC21-AFLADB22, and ICC21-AFLCDR22.
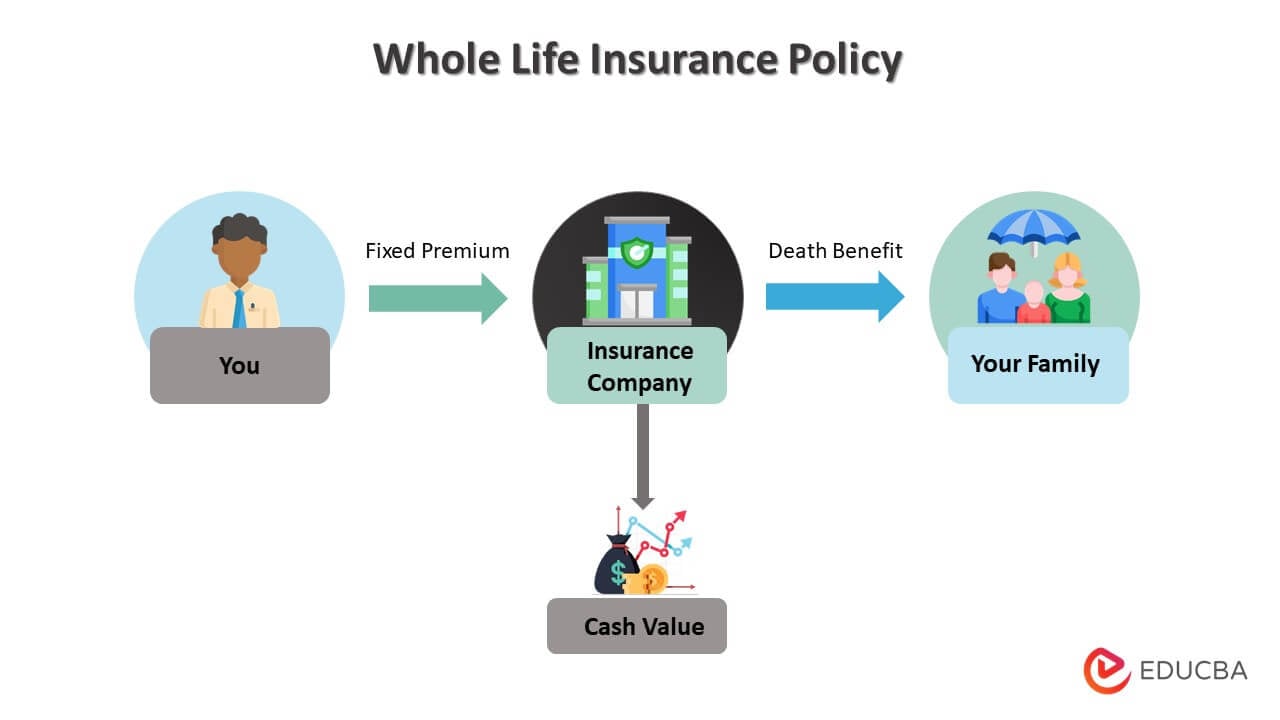
Coverage/plan levels might not be available in all states, including but not limited to NM or VT. Benefits/premium rates may differ based on plan selected. Optional riders might be available at an additional expense. Policies and riders may likewise include a waiting duration. Describe the exact policy and rider forms for benefit details, meanings, constraints and exemptions. In this short article, we describe what whole life insurance is and compare it to describe life insurance, in addition to universal life and variable life insurance coverage. We likewise discuss how entire life works and why lots of people prefer it over term. Before we jump into this subject, we need to respond to one essential concern: What is entire life insurance? Just put, it's a kind of insurance coverage that guarantees protection for the life time of the insured as long as premiums are being paid. Whole life insurance also ensures the premiums and expenses will never ever increase. Whole life insurance coverage is one type of long-term insurance coverage and is very various from term life insurance coverage, which offers coverage for a given duration just and does not develop cash worth. This short article discusses how entire life insurance works Lots of people believe of life insurance just in regards to a survivor benefit. Numerous of those features, sometimes called living advantages, are highly preferable, andthis is importantthose features
The Mechanics of Whole Life Coverage
can not be found in any other kind of financial product on earth. If term life insurance coverage is the most typical form of life insurance, whole life insurance coverage is the earliest kind of irreversible life insurance.(Two exceptions are suicide within the very first 2 years, and resting on the insurance application.)On the other hand,"term policies are mainly developed to last only for a finite period of time that will likely end before you pass away. "Having an insurance coverage that is ensured not to expire before you do indicates that a policy you bought to offer security for your household will safeguard them, anytime you die. You'll also get a totally free chapter from Pamela Yellen's New york city Times very popular book on this topic.] Entire life insurance includes an element that term life insurance coverage does not have. Part of your premium goes toward a savings portion of your policy. This is called the cash value of your policy. This allows policies to be created so that no more premiums are due once you retire, for example. You can secure a loan at a rate that is often lower than banks use.
Insurance in Rancho Cucamonga CAThe larger your cash value, the larger the loan you can take. You can utilize your cash value to supplement your other retirement earnings. Whole life insurance is the only kind of life insurance that ensures of the following: The death advantage won't go down The policy will not end as long as premiums are paid Your premiums will not
Insurance in Rancho Cucamonga CA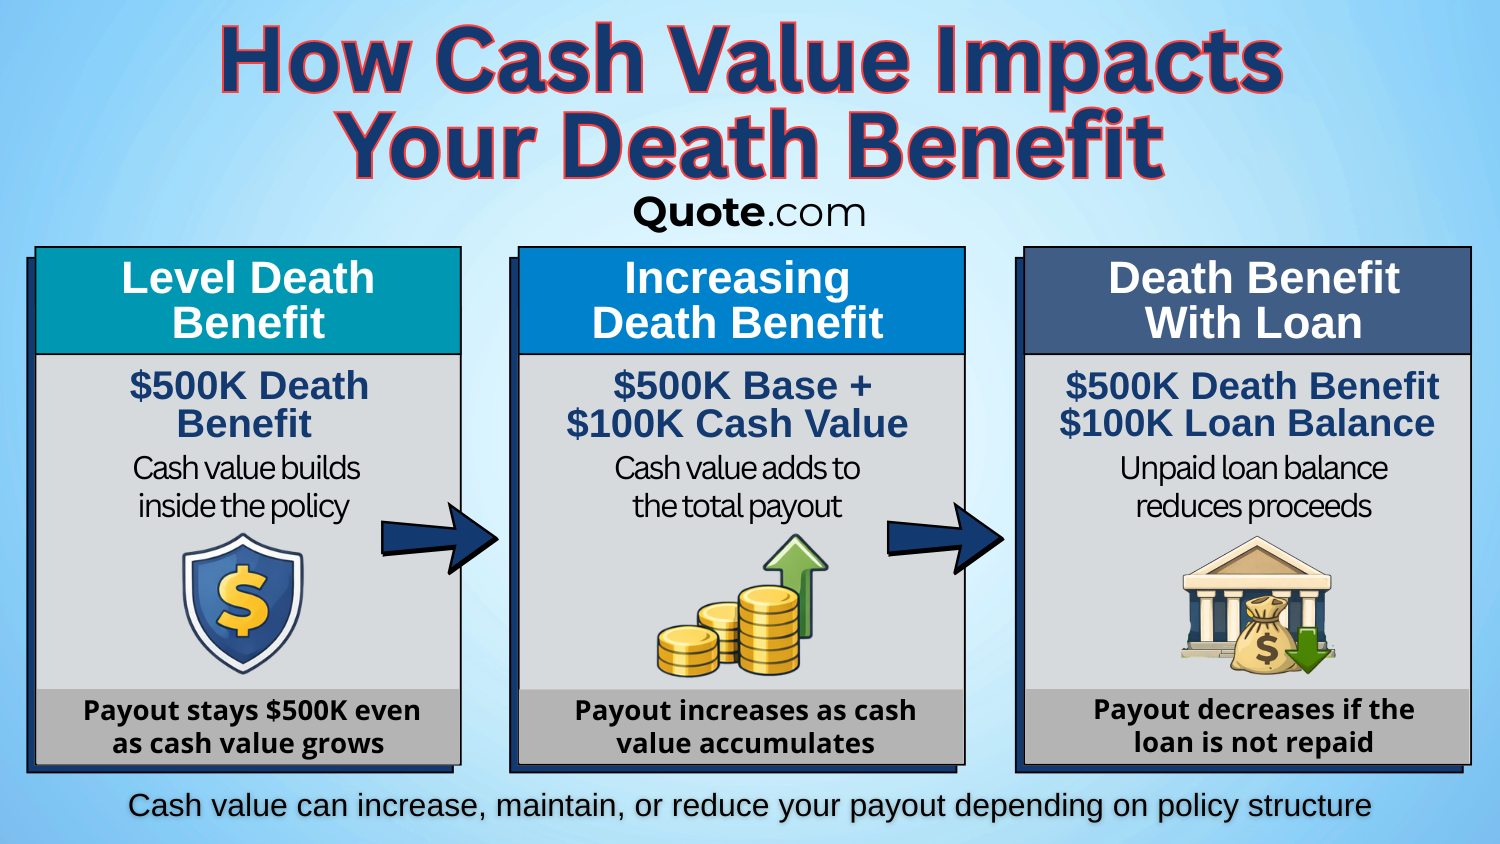
go up Your costs will never increase The insurance provider guarantees that the cash worth of your entire life insurance policy will grow gradually. figure out just how much your cash worth ought to grow based upon current rate of interest, which, obviously, differ in time. allow you to invest funds in policy subaccounts, comparable to shared funds. Your cash value will increase orreduce, depending upon the performance of these subaccounts. What occurs if performance of the money worth of your universal or variable life policy drops? Who needs to ante up more premium to keep your policy in force? You do. Neither choice is great. If you have a whole life policy, you will not need to make those horrible choices. The premium, cash worth, and survivor benefit are all ensured. And did you understand you can learn exactly what your guaranteed premium, money value and death benefit will be at any time before you choose if it makes good sense to start a whole life policy? Simply request a FREE, no-obligation Analysis here to take the very first step. In a way, it resembles getting an income tax refund. Now, dividends are not ensured. It's imaginable an insurance coverage company might have a horrible, awful, no great, very bad year . That's what the company plans for. And every year that'sbetter than they prepared, they can pay a dividend. Get Your FREE Report! Get instantaneous access to the FREE 18-page Special Report that reveals how super-charged dividend paying whole life insurance coverage lets you bypass Wall Street, fire your banker, and take control of your financial future. You get to tell the insurer what to do with your dividend. and this just may be the neatest thing considering that cupcakesyou can have them use your dividend to buy more insurance coverage for you insurance coverage you'll never ever have to pay another premium for once again. Think of that! You can buy additional insurance coverage that's paid up, implying no more premiums will be due on that additionever. If that advises you of the eighth marvel of the worldcompound interestthat's due to the fact that the idea is exactly the very same. Just paid up entire life insurance coverage additions develop both your policy's money worth and your death advantage. You can find out more here about dividend-paying entire life insurance coverage, which lots of people discover particularly amazing. Term life insurance premiums go upsometimes drasticallywith every brand-new term, because much of the cost of insurance is based on how likely you are to die at a provided age, and as you get older, that likelihood goes up. Universal and variable insurance coverage premiums can increase, tooagain, in some cases drasticallyif cash worth drops dueto low rates of interest or poor financial investment efficiency. You may be asking, "If it costs more to insure my life with every death year, how can a life insurance coverage business assure my premiums will never ever go up?" The answer is elegantly simpleand it helps describe why whole life insurance is more costly than term insurance in the early years of the policy.

Latest Posts
Life Insurance Solutions for Veterans

Securing Coverage for Families

Burial Insurance Strategies for Families